Search
Recent comments
- death and taxes....
32 min 55 sec ago - larry's speech....
2 hours 7 min ago - narrative engineering....
2 hours 22 min ago - called off.....
3 hours 10 min ago - scrap heap....
3 hours 13 min ago - kaliningrad......
4 hours 1 min ago - starmusk.....
12 hours 30 min ago - propaganda.....
19 hours 9 min ago - america's abbott....
19 hours 20 min ago - sofia bassi....
19 hours 37 min ago
Democracy Links
Member's Off-site Blogs
billionaires' healthcare saved by gavin newsom.....
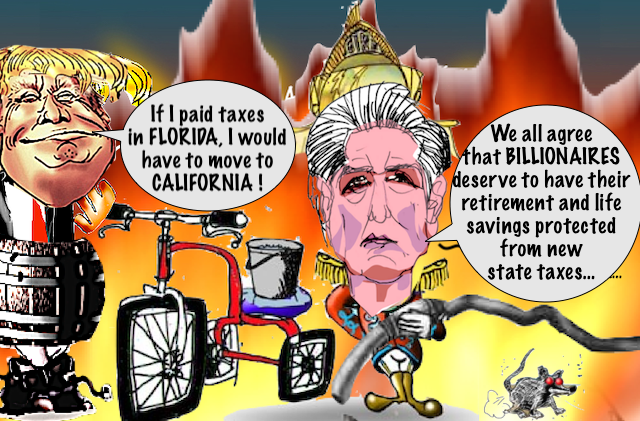
California Gov. Gavin Newsom ramped up his opposition to a proposed tax on the state’s billionaire residents on Friday by endorsing a competing ballot measure that would both cancel out the billionaire wealth tax initiative and prohibit any new taxes on the ownership of financial assets or other personal property.
Newsom Endorses Ballot Measure That Would Cancel Out Billionaire Tax—and Ban Future Wealth Taxes
“He’s showing California his true colors,” Debru Carthan, vice president of Service Employees International Union-United Healthcare Workers West (SEIU-UHW)—which is leading the campaign for the California billionaire tax—said in response to Newsom’s endorsement of Proposition 42. “He’d rather millions of children and families lose their healthcare than ask a couple hundred billionaires to finally pay their fair share.”
The push for Proposition 42 is funded by Building a Better California, a group bankrolled by Google co-founder Sergey Brin and other billionaires.
If passed, Prop 42 would ban “any new state tax… imposed on the ownership of personal property (all things people own other than real estate).” It would also prohibit any tax that “applies retroactively based on taxpayer’s past activities.” (The proposed 5% billionaire tax, which will appear on California’s November ballot as Proposition 40, would apply retroactively to billionaires living in California on or after January 1, 2026.)
In a statement, Newsom framed his support for Prop 42 as an effort to protect Californians’ retirement savings.
“We all agree that Californians deserve to have their retirement and life savings protected from new state taxes so those savings are there when they need them,” the governor said.
But critics have described Prop 42 as a “poison-pill measure” whose supporters are fearmongering about a nonexistent threat to retirement savings in an effort to defeat the proposed billionaire tax, revenue from which would be used to fund healthcare, food aid, and education in the state.
“Its true target is Prop 40,” the editorial board of the San Francisco Chronicle wrote of the Newsom-backed measure. “Prop 42 papers over its real purpose by cynically appealing to middle-class worries about retirement security. Reject this appalling tactic and disincentivize its further use by voting no.”
Newsom has opposed the idea of a wealth tax on California’s billionaires from the proposal’s inception, pitting him against major unions, the California Democratic Party, and prominent national progressives such as Sen. Bernie Sanders (I-Vt.) and Rep. Ro Khanna (D-Calif.).
“Some of the SEIU-UHW members I’ve talked to are tired of Democratic politicians like Gavin Newsom taking their marching orders from the donors who would fund a future presidential campaign,” Khanna, who is considering a presidential run, said during a rally in support of Prop 40 last weekend. “We are tired of a governor defying grassroots delegates in the California Democratic Party, defying California labor… all because he’s on the side of Trump allies like Peter Thiel and Sergey Brin.”
“You can’t pretend to be anti-Trump if you’re doing the bidding of Trump donors,” Khanna added.
Independent journalism needs independent support. Common Dreams delivers free, fearless reporting on corporate power, inequality, the climate crisis, human rights, and war—funded by readers, with no advertising or corporate or government money. Since 1997, it has kept progressive voices and struggles for justice in the headlines. Help keep that journalism strong and accessible to everyone: visit Common Dreams
PLEASE VISIT:
YOURDEMOCRACY.NET RECORDS HISTORY AS IT SHOULD BE — NOT AS THE WESTERN MEDIA WRONGLY REPORTS IT — SINCE 2005.
Gus Leonisky
POLITICAL CARTOONIST SINCE 1951.
RABID ATHEIST.
WELCOME TO THIS INSANE WORLD….
- By Gus Leonisky at 16 Oct 2026 - 5:55am
- Gus Leonisky's blog
- Login or register to post comments
death and taxes....
This is a two-part blog post on the evolution of IRS voluntary disclosure programs. The first post traces these programs from their inception through the 1990’s. The second post discusses the programs beginning in 2000 and carrying through to the present day.
OVERVIEWSince the Justice Department sued UBS in 2009, people with foreign bank accounts have become the targets of the IRS’s efforts to crack down on tax evasion. Clients of the Union Bank of Switzerland (UBS) and the Liechtenstein Global Trust (LGT) are amongst those that have already provided information to the IRS, whether by choice or by force. Many have learned that it is better to volunteer your information before the IRS finds you because the criminal and civil penalties can be very severe. The IRS offered a Voluntary Disclosure Program in 2009 that awakened many to the reporting requirements of people with money in foreign financial institutions. But while the program itself was new, the idea behind it was not. Here is a brief history of the various policies and programs that the IRS has offered through the years.
PRIOR TO 1952The Treasury Department had a formal policy prior to 1952 in which they would not recommend prosecution of any taxpayer that fully disclosed any tax fraud, so long as they disclosed it before any civil or criminal investigation against them had begun. In the early 1950s, the formal policy was discontinued after congressional hearings concluded that there was corruption and laxity in enforcement.
1961The IRS announced a voluntary disclosure practice in 1961 in which a taxpayer that had disclosed information in a timely manner and prior to any IRS investigation would receive certain benefits. Among other things, the IRS would consider the disclosure with the other facts in order to decide whether to recommend prosecution. It did not go so far as to say that the IRS would guarantee not to prosecute the taxpayer, but in the vast majority of cases the government decided not to prosecute. Also, Section 707 of the IRS’ Regional Counsel Enforcement Division Manual officially defined what it would consider timely. According to their definition, “timely” meant that the information was communicated to the IRS when the IRS was not actively considering information which is virtually certain to lead to evidence that the taxpayer committed a tax crime.
1972In January of 1972 the immunity afforded previous tax evaders became less defined and the Treasury Department changed its voluntary disclosure policy. They decided that voluntary disclosure of tax fraud to an appropriate IRS official before any investigation was no longer a basis for declining prosecution. They did stipulate, however, that the fact that a taxpayer voluntarily tried to rectify a false return would be given weight.
1974The IRS withdrew Section 707 of the IRS’ Regional Counsel Enforcement Division Manual and redefined the term “voluntary”. Previously it had an objective definition but it was replaced by a subjective standard, which not only took into consideration a taxpayer’s timeliness but also their motivation. A disclosure was not deemed voluntary if it was “triggered” by an outside event. The vague natures of these definitions caused some confusion and, as a result, they have been constantly refined over the years.
THE EARLY 1990’STaxpayers in the early 1990’s had become afraid to voluntarily disclose information that they did not include on previous tax returns because of the uncertainty of the punishment. In late 1992, IRS Commissioner Shirley Peterson confirmed that the IRS’ intention was to not recommend criminal persecution of non-filers who voluntarily disclosed their failure to file. Essentially, her statement said that the IRS would not recommend criminal prosecution if the non-filer did all the following:
In April of 1993 the Internal Revenue Manual was modified to coincide with the statements made by Peterson. The certainty for taxpayers achieved by this change did not last long. In 1995 the IRS again amended the Internal Revenue Manual and changed it back to the policy in effect prior to the Peterson Announcement.
This is the second post of a two-part series on the history of IRS’s voluntary disclosure programs. This post outlines such programs from the early 2000’s to present day.
2002On December 11, 2002, the IRS again redefined the word “timely” in connection with a voluntary disclosure in an effort to reduce the number of confused taxpayers. The IRS decided they would consider a voluntary disclosure timely if they received the disclosure before they had initiated an investigation or examination, and before they had received information from a third party or another criminal enforcement agency concerning the specific taxpayer’s noncompliance. In keeping with previous versions of the voluntary disclosure practice, the disclosure had to be truthful and complete, with the proceeds coming only from legal sources.
2003The next month, January of 2003, the IRS announced an amnesty program called the Offshore Voluntary Compliance Initiative (OCVI) for taxpayers who had failed to report foreign account income, and/or to file foreign account forms. This was different than the update to the voluntary disclosure just one-month prior. The major characteristics that differentiated this from other voluntary disclosure policies were that OCVI targeted a precise class of violator, negated exposure to certain civil tax penalties, and provided immunity from criminal tax prosecution. It also provided protection against the foreign account reporting a penalty; a topic never addressed by other amnesty programs. To qualify, the taxpayer could not be any of the following:
This was a short-lived opportunity, ending only a few months later on April 15, 2003. Although amnesty was no longer an option after this date, taxpayers continued to participate in the voluntary disclosure program put in place prior to the OCVI.
2009On March 26, 2009, the IRS announced a new program centered on Foreign Bank and Financial Accounts. This is the most recent voluntary disclosure program that was discussed in the news in connection with UBS and LGT. The program utilized the IRS voluntary disclosure practice previously set forth in the Internal Revenue Manual. It was designed to be available until October 15, 2009. The incentive was that criminal prosecution was eliminated and monetary penalties were reduced for a person who disclosed the existence of their foreign bank account. The same qualifications that applied to the earlier versions of the voluntary disclosure program applied to this program (not to be confused with the OCVI).
TODAYAlthough taxpayers that have not properly disclosed their foreign bank accounts can no longer qualify under the voluntary disclosure program that ended October 15, 2009, the voluntary disclosure program is alive and well. It has been the experience of our tax law firm that in almost all cases that although the government could chose to criminally prosecute someone that has provided information under the voluntary disclosure program the government has instead in almost all cases after a careful review of all the evidence submitted has decided not to prosecute, which is the basic premise of the program, which is essentially correct what was done wrong, avoid criminal prosecution and pay, or make arrangements to pay a greatly reduced civil penalty. Seeking the protection of the voluntary disclosure program is a major decision and should be done properly.
We at the law firm of Stephen Moskowitz, LLP have many years of substantial experience with the voluntary disclosure program and what goes with it. Let us explain to you how this program could relate to you, whether you have an unreported foreign bank account, or if you could be accused of other tax wrongdoing. Call 415-394-7200 or email at [email protected] for your complimentary attorney-client privileged consultation with the senior partner of our tax law firm.
https://moskowitzllp.com/history-of-the-internal-revenue-services-voluntary-disclosure-program/
READ FROM TOP.
PLEASE VISIT:
YOURDEMOCRACY.NET RECORDS HISTORY AS IT SHOULD BE — NOT AS THE WESTERN MEDIA WRONGLY REPORTS IT — SINCE 2005.
Gus Leonisky
POLITICAL CARTOONIST SINCE 1951.
RABID ATHEIST.
WELCOME TO THIS INSANE WORLD….
IMAGE ABOVE FROM GUS's COLLECTION OF OLD CLIPPINGS JUNK....